

Digital Experience Strategy in Fintech: How UX and DX Differ and Work Together

TL;DR
A payment app can score well in task-based testing and still see customers drift away within the first month. The damage happens in moments that task success alone does not measure. UX makes each moment worth trusting; DX decides whether those moments add up to a company people keep their money with.
Why Both Matter Now:
- Over 60% of retail banking customers bank exclusively through digital channels (Capgemini)
- 20% moved money away from their primary bank within three months (J.D. Power)
- The interface may soon belong to someone else—customers are handing banking to AI assistants
The Article Goal: to give you a framework for seeing where UX and DX differ in fintech and how to make them work together, so a team knows which moments to fix first, how to brief them, and how to measure the result.
In fintech, trust builds gradually and one bad moment can put it at risk. User experience (UX) makes each moment worth trusting, and digital experience (DX) keeps the relationship consistent across the app, the website, the emails, and the support. In fintech, “DX” often means developer experience. Here it means digital experience, the customer’s experience across every digital surface a company owns.
A team that invests only in UX ends up with products that are easy to use in isolation and harder to trust over time. A team that invests only in DX ends up with a consistent company around a product that is hard to use.
The two are often mentioned together, and each has its own scope and its own value. Seeing where they differ is what lets a team make them work together.
What Is the Difference Between UX and DX in a Fintech Product?
UX is not a stand-in for “does the button work.” It covers usability: is a flow learnable, efficient, and forgiving of mistakes. It also covers the emotional side of using a product: does it feel fast, safe, and worth coming back to. Nielsen Norman Group has held the same bar since 1998: an exemplary experience meets the customer’s exact needs “without fuss or bother.” That bar applies inside one product. It takes real craft to meet.
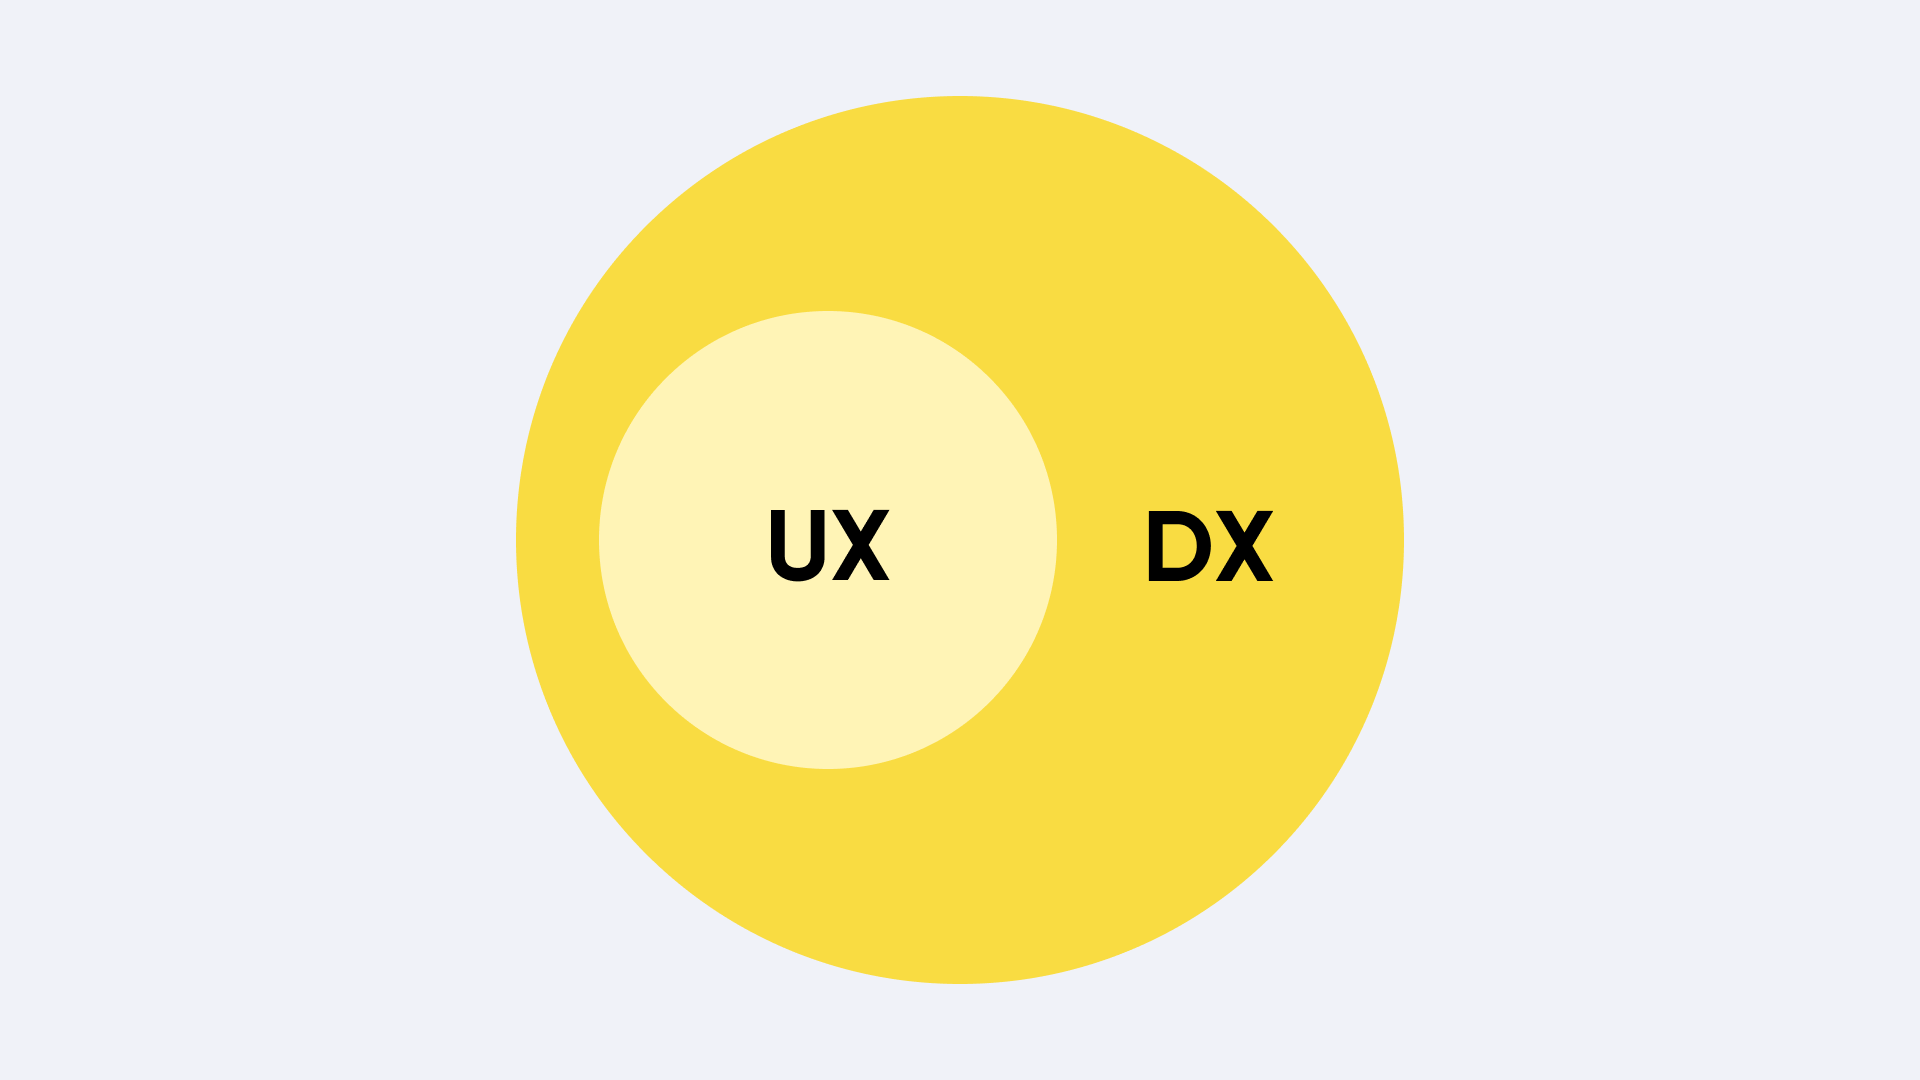
DX works at a different scale. It is what happens when that same standard holds consistently across every digital surface a company owns, not only one product. Adobe describes digital experience management as keeping a brand’s identity, messaging, and visual language uniform across every digital channel. That consistency is what builds recognition, trust, and loyalty.
Visual and verbal consistency is the visible part. The less visible part is continuity: a customer who starts a dispute in the app should not have to repeat it to support, and a limit changed on the website should show up in the app the same minute.
Some CX practitioners describe this directly as an intersection. UX shapes how a customer experiences one interface. DX is whether that experience holds up everywhere else the brand shows up.
A digital experience strategy is the plan that keeps both working together as a company adds products and channels. The brand side of this is covered in our guide to brand experience design.
That difference shows up in moments that task success alone does not measure.
When a Product Tests Well and Still Loses Customers Anyway
A payment app can score well in task-based testing because every flow is clean and fast. It can still see customers drift away within the first month. The cause is often the cumulative effect of a few moments:
- Notification cadence. Too many alerts about routine activity can read as noise, while silence during something unusual can read as negligence.
- Error message tone. “Transaction failed” is accurate, but it says nothing about whether the customer’s money is safe.
- Empty states. A new account with no history can look like a fresh start or like a product that has not finished loading.
- The moment after a decline. A declined card is a point where the customer is likely to worry about their money, and what the app says next shapes how the product is remembered.
Each one gets the task done, so a test that measures only completion will pass it. Inside one product, that is a UX gap, and good UX research catches it by also asking how the moment felt. It becomes a DX gap when the same moment plays out differently across channels.

Why Do UX and DX Both Matter in Fintech and Banking Now?
Digital is often the whole relationship. Capgemini’s 2025 retail banking research, cited in its Banking Top Trends 2026, finds that over 60% of retail banking customers bank exclusively through digital channels. In omnichannel banking, those touchpoints carry the whole impression of the institution.
Money moves quietly. J.D. Power studied 107,059 customers of the largest US banks. It found that 20% had moved money away from their primary bank within three months, up from 17% a year earlier. J.D. Power calls this soft switching and links it to cracks at key points of the customer journey.
The interface may soon belong to someone else. Forrester analyst Alyson Clarke writes that customers are starting to hand banking conversations to third-party AI assistants. The bank risks becoming the backend, which raises the stakes on staying consistent wherever customers meet it.
The trends are industry-wide. Where they hit depends on the product: which moments make customers anxious, how often they happen, and whether a bad one can be repaired.
How to Find Where UX and DX Actually Diverge
Ask two questions about each important moment instead of one. The UX question: does it work, and does it feel right in this product? The DX question: does it look, sound, and behave like the same company everywhere else?
For example, those six moments can show the gap:
- Onboarding. UX: is it efficient and forgiving if the customer makes a mistake? DX: does it match what they were promised before signing up?
- Declines and errors. UX: can the customer recover quickly, and does the message lower anxiety rather than raise it? DX: does it sound like the same company as everything else they send?
- Notifications. UX: is the tone and timing right for the moment? DX: do push, email, and SMS sound like one voice?
- Support handoffs. UX: is the handoff itself fast and low-friction? DX: does the agent sound like the same company as the app?
- Consistency. UX: does each surface meet a high bar on its own? DX: do the app, emails, and website feel like one company?
- Time. UX: how did the product perform this session, by the usual measures? DX: which metric would notice a customer who is active but trusts the company less than last quarter?

For onboarding, we broke down where fintech flows lose users in a separate article.
Three properties decide which gap to close first: emotional load (how much money anxiety), frequency (how often), and recoverability (whether the impression can be repaired). Start where load and frequency are high and recoverability is low.
Once the gap is visible, the work changes: how it is briefed and measured.
What Changes When UX and DX Work Together
When UX and DX are planned as one experience, two conversations change.
The brief. “Make onboarding faster” is a UX brief. “Make onboarding deliver what the website promised” is a DX brief. A joint brief asks for both: onboarding that is fast and matches what customers were told before they signed up.
The measurement. Task metrics show whether the product works. Behavior shows whether customers trust the company: whether they deepen the relationship over time and how they act after a stressful moment such as a declined payment or an outage. Tracked together, the two show both how the product performs and whether the relationship is growing.
Conclusion
UX and DX each have their own value. UX makes every moment of a product work and feel right. DX makes those moments add up to a company customers recognize and trust enough to keep more of their money with. A digital experience strategy is what keeps both moving together as a fintech product, team, and company all grow.
That is the work Qubstudio does. We are a Digital Experience Design Agency. Over 19 years, we have delivered 700+ projects, much of it in fintech and banking across the USA, GCC, and Europe. We work on both: UX inside each product, and DX across all of them. We help teams move from “our product is easy to use” to “our product is a financial relationship people want to stay in.”
The teams that lead the next phase will be the ones whose customers, a year in and after at least one bad moment, still choose their product.
Let's Talk About Your Digital Experience
FAQ
What is the difference between UX and DX in a fintech product?
UX covers usability inside one product: is a flow learnable, efficient, forgiving of mistakes, and does it feel fast and safe.
DX works at a different scale: whether that standard holds across every product, the website, and the brand. Weak UX loses customers at the first task; a consistent brand around a hard-to-use product loses them just as fast, only later.
Why do UX and DX both matter in fintech right now?
Capgemini finds over 60% of retail banking customers bank exclusively through digital channels, so those touchpoints carry the whole impression.
Forrester analyst Alyson Clarke also notes customers are starting to hand banking conversations to third-party AI assistants, risking the bank becoming just the backend.